Malaysia’s Data Centres Run at 40% of the Power They Reserved. That Is the Real Bottleneck.

The Fastest Build in Southeast Asia, Then a Pause
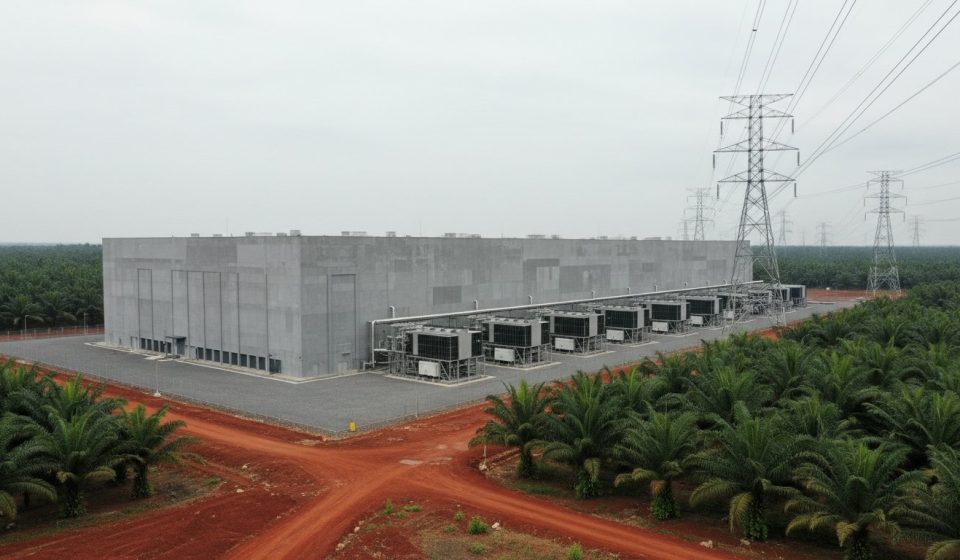
Malaysia went from roughly 10 megawatts of data centre capacity in 2021 to about 1.3 gigawatts by 2024, on DC Byte’s numbers. At one point more than two-thirds of all data centre capacity under construction across Southeast Asia’s five main economies was committed to Malaysia, most of it in Johor, the state across the causeway from Singapore. Johor is projected to hold around 60% of national capacity by 2030.
Then the approvals slowed. An informal moratorium has shaped decisions since roughly mid-2024 without ever being announced. In February, Prime Minister Anwar Ibrahim said applications for data centres unrelated to high technology and AI had already been stopped. Johor rejected about 30% of new applications in 2024, and some electricity and water approvals have taken up to 18 months.
The obvious reading is that Malaysia got cold feet about power. The numbers say something more specific, and more interesting.
Reserved Power Versus Used Power
Malaysia’s data centres were consuming 603 megawatts against a declared maximum demand of 1,276 megawatts — about 40% utilisation. The government’s stated target is 85%.
That gap is the heart of the problem, and it has nothing to do with generation capacity.
When a developer signs an electricity supply agreement, the declared maximum demand is booked against the grid. The utility must plan for it: transmission, substations, reserve margin. Whether the servers ever arrive is the developer’s business. So a project at 40% utilisation is holding roughly 60% of its grid allocation idle — reserved, planned for, paid for by the system, and not producing anything.
Multiply that across a pipeline growing this fast and the queue fills with reservations rather than load. New entrants with real demand wait behind speculative ones. That is why an approval pause can be a rational grid-management tool rather than a retreat from the sector: it is cheaper to force utilisation up on existing allocations than to build transmission for demand that may be notional.
Water Is the Harder Constraint
Electricity can be built. Malaysia plans to add 6 to 8 gigawatts of gas-fired generation and up to 10 gigawatts of renewables by 2030, against projections that data centres could need 5 to 6 gigawatts by 2035.
Water is different. As of 2024, the national water regulator SPAN had received 101 data centre applications requesting a combined 808 million litres per day. It approved 45 of them, for 142 million litres per day — under 18% of what was asked for.
That is not a permitting backlog. It is a regulator telling an industry that most of what it requested does not exist. Johor has been warned about drought risk, and cooling water competes directly with household supply in a state that has had supply problems of its own. Some operators in Johor have responded by buying their own water rather than drawing on public supply.
An AI data centre can be redesigned to use less water — closed-loop or air cooling, higher operating temperatures — at a cost in efficiency and capital. The projects that clear Malaysian permitting from here will be the ones that did that design work up front.
Why This Matters Outside Malaysia
Johor grew into a data centre hub partly because Singapore stopped approving new capacity in 2019, and the industry looked across the border. Singapore reopened in 2022, but with hard limits: roughly 60MW of new capacity a year, around 5MW per facility, and a power usage effectiveness requirement of 1.3. Now the overflow destination is rationing too.
The pattern is worth naming: AI capacity is mobile until it meets a physical constraint, then it moves again. Each move buys a few years. The constraint is not land, capital or chips, but the two things a data centre consumes constantly and cannot ship in — electricity and water.
For anyone planning AI infrastructure in emerging markets, the diligence question is not whether the local government welcomes investment. It is whether the local utility and water regulator have signed, and at what declared demand.
What to Watch
- Utilisation-linked approvals. If Malaysia starts granting new allocations on the basis of proven load rather than declared demand, expect other grids to copy it. It is the most direct fix for a queue full of reservations.
- Whether the 85% target is enforced or aspirational. A target with no consequence for missing it changes nothing.
- Water approval rates. Under 18% was the 2024 picture. If that rate stays flat while the pipeline grows, the gap between announced projects and buildable ones will keep widening.
If you are tracking announced data centre capacity anywhere, treat the megawatt figure as what it is: a reservation, not a building. The number worth having is utilisation against declared demand. Malaysia has published it — 40% against an 85% target — and that single ratio explains its approval pause better than any statement about welcoming investment does.
Get the weekly briefing
One email a week on AI, infrastructure, policy and the supply chains underneath them. Free, and you can unsubscribe any time.